In an era of uncertainty, investors should focus on understanding what they own, evaluating risks beneath the surface of broad benchmarks and maintaining a long-term perspective to ensure they are best positioned to adapt and create long-term value.
Investor concerns vary by geography, market and mandate – but there is often a common thread. Whether they are discussing artificial intelligence (AI), geopolitics, public markets or the economy, the underlying concern is often the same: uncertainty. What is striking, though, is that for many of them, today’s version feels different.
Investors have always had to navigate uncertainty, but historically, it has been tied to a singular event or cycle. What we’re experiencing now is broader and more structural, driven by three powerful forces reshaping markets simultaneously: extreme equity market concentration, geopolitical decoupling and the rise of AI, including its potential to disrupt current business models and labour markets.
One consequence for investors is that the gap between winners and losers may widen. Companies operating in the same markets, sectors or industries can face very different opportunities and risks. In this environment, the ability to navigate complexity, understand its implications company by company and practice selectivity will be increasingly important.
Market concentration is raising new questions
The current equity market is unusually concentrated. The top 10 companies account for nearly 38% of the S&P 500, and US equities represent about 70% of the MSCI World Index. Concentration also pervades US markets at both the industry and sector levels; semiconductors alone represent 17% of the S&P 500, and the IT sector as a whole represents 38%. These are concentration levels that deserve attention.
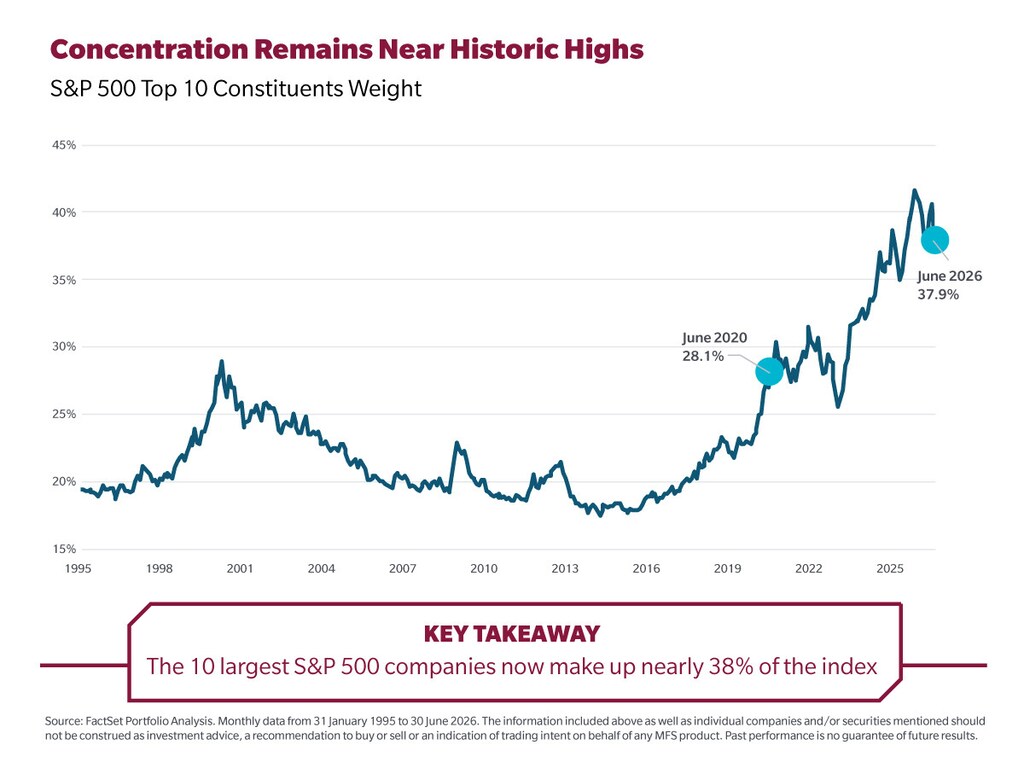
Concentration is not necessarily a problem on its own. Markets often reward the strongest companies, and many of today’s leaders have earned their positions through innovation, scale and execution. But concentration elevates important questions about portfolio construction and risk management.
History shows that concentrated leadership can unwind in different ways. The Nifty Fifty – 50 large-cap stocks on the NYSE known for consistent earnings and high price-to-earnings ratios in the 1960s and 1970s – declined gradually as inflation and economic headwinds compressed valuations. The late-1990s technology bubble unwound much more quickly, with the Nasdaq Composite falling sharply between 2000 and 2002. Investors rarely know which path markets will take.

Broad exposure may still play an important role in portfolios, but in a more concentrated market, investors need to understand what they own, why they own it and where risks may be concentrated beneath the surface.
Geopolitical fragmentation is reshaping global trade
For decades, companies built global operations around increasingly integrated markets and supply chains optimized for cost efficiency rather than resilience. Trade and investment relationships are becoming more fragmented.
The US–China relationship is a prominent example, with strategic competition intensifying around semiconductors, AI and critical minerals. Export controls have expanded, industrial policy has reemerged as a tool of national security strategy and political considerations increasingly influence trade negotiations.
Companies that once optimized for efficiency and global integration must now optimize for resilience, regulatory complexity and geopolitical optionality. One semiconductor company may depend heavily on access to global markets that export controls could restrict. Another may benefit from policies supporting domestic manufacturing but face substantial capital requirements and long payback periods. Both are exposed to the same geopolitical shift, yet the implications for their revenues, capital allocation and long-term strategies may differ significantly.
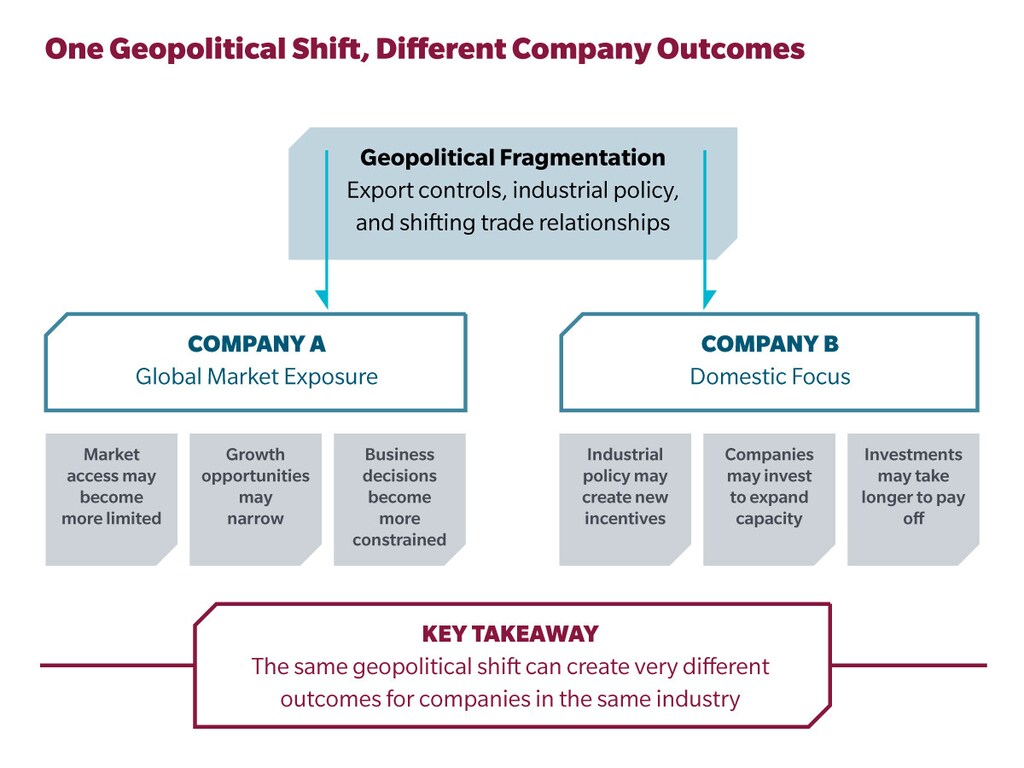
Geopolitics is therefore becoming a direct driver of company-level outcomes. In a fragmented world, the same policy or trade development can create different risks and opportunities across companies, sectors and regions. Understanding those differences requires deep research and selectivity.
AI is reshaping competitive advantage
Artificial intelligence represents a profound economic inflection point. But one of the risks for investors is treating AI as a single theme. Even among companies broadly viewed as AI beneficiaries, the business implications can be very different.
A company integrating AI into subscription-based enterprise products may have a different monetization path, funding structure and margin profile from a company using AI primarily to improve advertising performance or develop new consumer platforms. Investors must consider not only potential growth, but how that growth will be funded, how long it may last, and whether it will strengthen the company’s competitive advantage.
The same question applies beyond the largest technology companies: which businesses become stronger because of AI and which become more vulnerable? In software, applications embedded in complex workflows that require trust, compliance and accountability may be difficult to displace. Software serving primarily as a data repository or supporting repetitive workflows with low switching costs may be more vulnerable.
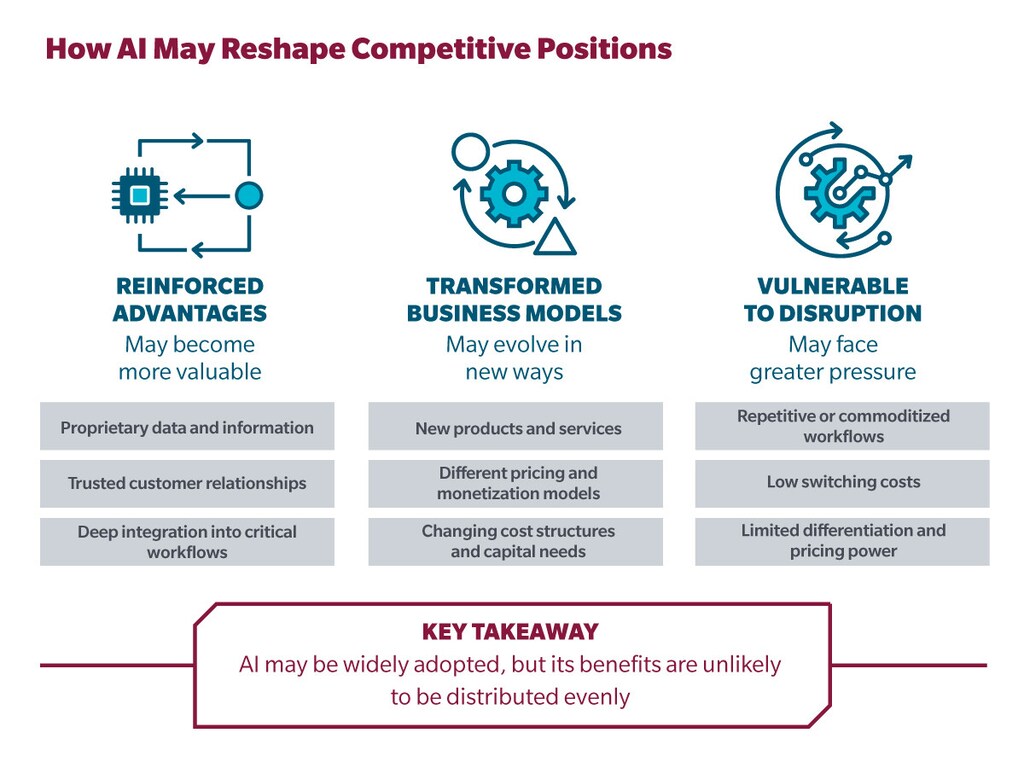
The difference may depend on access to unique, high-quality data, integration into proprietary workflows, regulatory expertise, intellectual property, capital discipline and management execution. The key distinction is not which companies are using AI, but which companies will become stronger because of it.
Navigating what comes next for investing
The future path of markets may be impossible to predict, but investors are not powerless in the face of uncertainty. They can focus on understanding what they own, evaluating risks beneath the surface of broad benchmarks and maintaining a long-term perspective.
Selectivity is not about knowing precisely what comes next. It is about recognizing that market concentration, geopolitical fragmentation and AI will not affect every business in the same way.
The reality is that uncertainty, in any of its forms, is unavoidable. But when outcomes are increasingly likely to diverge, understanding those differences may help investors identify the businesses best positioned to adapt and create long-term value.
These views should not be relied upon as investment advice, as securities recommendations, or as an indication of trading intent on behalf of any MFS investment product.




