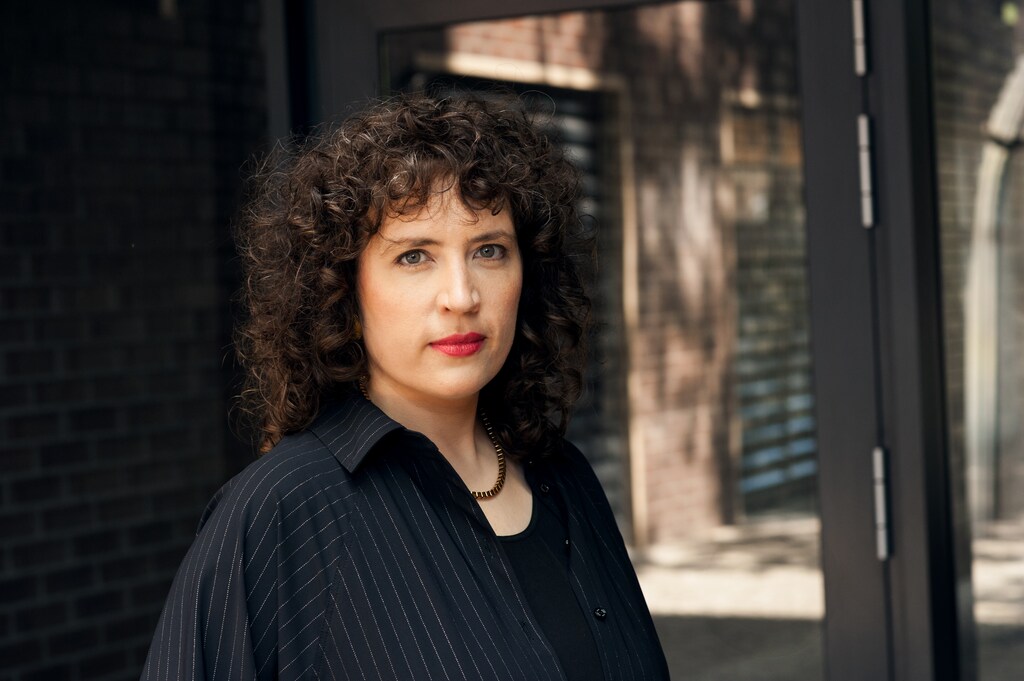
How can economic policy help strengthen democracy and stop cost of living crises pushing people into the arms of authoritarians? We hear from Isabella Weber, Associate Professor of Economics at the University of Massachusetts Amherst.
This transcript has been generated using speech recognition software and may contain errors. Please check its accuracy against the audio.
Isabella Weber: For a long time, elites have been telling people that democracy is the greatest political system that has ever existed, which is of course true. But then in the second sentence have said, unfortunately, even when it comes to your most basic needs, there's not much that we as your elected representatives can do for you. And if this happens, it should not be a surprise that people lose trust in democracy.
Robin Pomeroy: Welcome to Radio Davos, the podcast from the World Economic Forum that looks at the biggest challenges and how we might solve them. This week we hear from an economist who says economic policy has a big role to play in preventing political extremism.
Isabella Weber: If we have a civic duty to prevent the return of fascism than economists to have a responsibility.
Robin Pomeroy: Isabella Weber has just published a book called Anti-Fascist Economics, which argues that societies that rely purely on market forces will end up being run by anti-democratic parties. The polarisation of politics in the West and elsewhere, and the rise of street unrest in Europe, she says, make this conversation more urgent than ever.
Isabella Weber: I think it's absolutely remarkable that we see like hundreds and thousands of people out in the street protesting over the cost of living, right? So what people are saying is we can't take the status quo any longer.
Robin Pomeroy: Follow Radio Davos wherever you get podcasts or visit wef.ch/podcasts. I'm Robin Pomeroy at the World Economic Forum and with this conversation with Isabella Weber about economics and democracy.
Isabella Weber: People are saying we can't take the status quo anymore and we need to provide a democratic way out.
Robin Pomeroy: This is Radio Davos.
Welcome to Radio Davos. Once again, we're talking about the economy. Once again I'm joined by my colleague, John Letzing. Hi John, how are you?
John Letzing: I'm very good, thanks Robin.
Robin Pomeroy: It's great to see you. You've got a great interview with us today. Fans of the show will know you from the interviews you do every four months or so with the chief economist around the time of the publication of the World Economic Forum's Chief Economist Outlook. This one. Is kind of, you know, extracurricular that you, you went out and suggested talking to Isabella Weber, if that's how you pronounce her name.
John Letzing: That is, yeah.
Robin Pomeroy: Tell us something about Isabella and why you wanted to talk to her.
John Letzing: Well, she's an economist and she has a very timely book that she has just released. It is called Anti-Fascist Economics. And really what it's about is finding ways to ensure that democracies endure and thrive. And that is obviously something that is a topic, very, very, popular topic these days.
Robin Pomeroy: It's an interesting, provocative title. What would you say the kind of the key thesis of it is?
John Letzing: I would say her main thesis, and she has really been talking about this for a while, but events have sort of caught up with her, it is that essentially the essentials need to be affordable for people in order for democracies to endure. And the way that economies tend to be managed these days does not focus on that. It's more of a blinders-on approach where economists are looking at supply and demand curves and trying to make the numbers work and fighting inflation as much as possible. And if people suffer in the meantime, hopefully it's not too much.
Robin Pomeroy: She could be considered a left-wing economist, right? That's what people would describe her as.
John Letzing: I suppose, yeah, you could frame things that way. She made some waves a few years ago as everyone was debating this explosion of inflation that came out of COVID and the emergency responses to that pandemic. She suggested in some cases we might want to consider things like price controls and that for many mainstream economists is a no-go zone. So people got bent out of shape. People went a little overboard actually, in many ways, but as I said, I mean, events have sort of caught up to her in many way.
Robin Pomeroy: What events are you referring to?
John Letzing: Well, you may have heard of this thing called affordability. It's, it's in the U.S. right now, for example, it is a very big issue. It is a huge issue in midterm elections that are, I know we are recording this as those elections are happening. It is election day today. And that's a huge, huge issue that hasn't gone away.
Now, inflation is not spiking in the way that it was a few years ago as we were coming out of COVID, but it has persisted. And it's enough has accumulated that people are still dealing with it and they're feeling like they're not able to catch up with the wages that they're earning.
Robin Pomeroy: Other events that maybe are catching up with this argument are protests in Europe, in places like France particularly, but lots of places, young people thinking they're disenfranchised and there's not really much of a future. Much of that argument comes down to money and economics, doesn't it?
John Letzing: Yeah, absolutely. And we do discuss the protest, the recent protests in France a bit. And I asked her, you know, can we see that as an example of the sort of predictable blowback to austerity or is that a reflexion of the limits of an anti-fascist economics? And I think, you know not surprisingly, she very much came down on the side of this is what we can expect from a sort of austerity or austerity light type regime where you are. Really starving people of a lot of things they would consider essentials, like education and the cost of food, for example. And you are just hoping that things will somehow get better and they won't make too much noise.
Robin Pomeroy: And so this expression anti-fascist economics, the danger she's saying here that if you have an economic situation where those essentials are just unaffordable to people, people will look to authoritarians.
She also though tries to put some solutions which you've already referred to, ensuring that things are absolutely essential, food, shelter, healthcare, housing are affordable. Some of those prescriptions though, as you've said it, what's the expression you use? Put people out of shape? Is that what you said? Bent them out of shame. Yes, bent them out of shape. Annoyed people. I think because perhaps you might say some of those prescriptions are kind of old school socialist things of rent controls or price controls. And if you were a free market economist. You would say the free market works much better and countries that have, and I know you put this to her in your interview, the Soviet Union tried to...
John Letzing: Pretty big example.
Robin Pomeroy: Provide, you know, in kind of a Marxist utopia type way, all the essentials to all the people. I think history has judged that as a failed experiment.
A lot of people who are free market economists or more inclined to think the free market works better than kind of dirigiste economics would say, ah, this is just, this old thinking, old left-wing thinking. She's saying, No, this is new thinking in some ways.
John Letzing: Yeah, it is. I mean, what she's essentially saying is it requires a more nuanced approach. You can't necessarily see things in these black and white trends. And if you do, the result might be a lot of anger, which as you say, can be exploited by politicians. So what she saying is, yeah, many of these things are already on the books. Many of these sort of ideas are already out there have been at least attempted. She talks about things like the World Food Board, which is the whole chapter of history I was unaware of, she talks about... Efforts in the 1970s to pursue full employment in the U.S., which really got blown up by a massive wave of inflation and then that very decisive effort to defeat that inflation. So yeah, the history is out there. What she's saying is don't look past these potential solutions just because they haven't had a chance really in history.
Robin Pomeroy: I think it's a really interesting conversation and no one's gonna adopt her policies in their entirety overnight, but I think what she's doing here with this book and with this interview with you is saying we need to address these things because as you've said, the events, the affordability crisis in pretty much probably everywhere around the world, these protest movements that we've seen in Europe.
And then we've not even mentioned it yet - get your bingo cards ready - artificial intelligence, which is already and is predicted to have a huge impact on the way economies work, on the labour market, in such a way that, you know, purely my own opinion, governments, publics, companies, are gonna have to reassess some of the fundamentals. Some of the things we took for granted maybe in the last few decades are going to be challenged by AI. So it's a good time to have these conversations, right?
John Letzing: Absolutely, there's so much unknown and we would love to believe that we're looking at a future where everyone is sort of retrained in new tools and continues to be employed, but we really don't know and if we want to talk about a future, where people are able to afford essentials, like you're saying, that's a pretty huge factor to consider.
Robin Pomeroy: It's an interview, John, that I think policy wonks and economist enthusiasts are going to enjoy, but I do want to make sure it's also accessible to people who don't spend their lives thinking about these things.
There are a couple of references. I've heard the interview already, for example, yeah, here's one. At some point, you and Isabella start talking about the Bretton Woods discussions, which as most people listening to this will be vaguely aware of at least was this kind of global meetings. During or towards the end of World War Two, I believe, which set up a lot of the international structures, like the International Monetary Fund, etc., etc., but where a lot of big discussions were had about economics. Isabella mentions a couple of economists who were there, Keynes and Hayek, and how they came to a certain agreement about something or other. Could you just remind us what Bretton Woods was and who those two were?
John Letzing: Yeah, it can be a bit confusing because these are towering figures in the history of economics, but people might not be fully aware.
Like you say, Bretton Woods was essentially another example of World War Two having really blown everything up, an effort to rebuild things, rebuild the global economy and shape it. Keynes is a reference to John Maynard Keynes. Hayek is a to Friedrich von Hayek. And these two are most often seen on opposing polls, because essentially Keynesian economics says, Hey, free markets are not always efficient. They don't always work the best for everyone. So governments need to intervene here and there to make sure that everything stays on an even keel. Now Hayek, on the other hand, would be aghast at that notion. According to Hayek and his vision of the world, um, you do not want to interfere with free markets if you are a government, because before you know you've landed in totalitarianism, even the best intentions are not going to lead to any good.
And in the middle of that, she also mentions another figure named Karl Polanyi, which people probably maybe are not so familiar with. He was an economic historian, more in the Keynesian mould. Essentially he did a lot of work on looking at how market economies. He calls it carried a virus and what he meant was that they tended to result in these sort of authoritarian phenomenon. So again, not very popular among the Hayek heads out there, that guy. So that's the essential dichotomy that she's referring to with these references.
Robin Pomeroy: Let's get to it then, John. This is your interview with Isabella Weber. She's at the University of Massachusetts Amherst. She's the author of this book, Anti-Fascist Economics. Here's your chat with her.
John Letzing: So I thought maybe we could start with some of your personal background. Maybe you could tell us a little bit about where you grew up and how that maybe informed what you refer to in the book as your first civic duty, which was anti-fascism.
Isabella Weber: Yeah, I grew up in Nuremberg where, you know, the just civilizational devastation that fascism left behind is something that you can see in the city every day. But then the mediaeval city walls, like around 70 percent of the old buildings were bumped to the ground and they were bumped into the ground for a reason. It's, of course, also the city of the Nuremburg Trials, which was important in setting the post-war order from a legal perspective. And it's a place that has been struggling with the heritage that the Third Reich left behind, concretely speaking, the rallying grounds of the Nazis that were set up and that are these monuments to their fantasies. And they are in Nuremberg for a reason because fascism thrives on this idea of a myth of a glorious past. And in this case, the a castle of Nuremberg became the anchor point for the myth of creating a Third Reich that is a sequel to the Second Reich.
John Letzing: It's very interesting that you can still see remnants of that there in the city today.
I thought maybe we could just to start off, just a very brief definition of what we mean when we say anti-fascist economics. If I could take a stab at boiling it down, it seems to me that it seems about reducing the economic anxieties that can be exploited for political purposes. I think you have a nice turn of phrase in the book where you refer to it as a direction of travel. So, I mean, do I basically have that right?
Isabella Weber: Yeah, I think it's helpful to clarify that it's not about anti-a-fascist economics, but that it is anti-facist economics in the sense that, you know, if we have a civic duty to prevent the return of fascism, then economists too have a responsibility and economic policy too plays a role in, you now, preventing the rise of the extreme right and even fascist forces.
The book was very much born out of my experience in the debates over how we respond to inflation, the inflation that was unleashed in the wake of the COVID-19 pandemic and the Russian attack on Ukraine, where I've been struck how, as economists, we debate big economic policy questions that have obviously massive implications for our societies without asking the question of how does our economic policy advice impact what's happening to democracy. And in the case of inflation, this has been happening amidst a tipping point in the rise of the extreme right globally speaking.
John Letzing: Another nice turn of phrase in the book is thinking about it as a means to address what you call the casual acceptance of existential pain, which is a really good way of putting it. I'm just wondering, is there an example of that in terms of the way economies are generally managed now, this casual acceptance that somebody listening to this might be to relate to.
Isabella Weber: I think actually inflation again is a good example here, right?
And we are just back at hiking rates. The ECB has hiked, the Fed has hikes, and we are hiking into a global oil price shock where the consequences of this oil price are on the one hand that people are being squeezed beccause of prices of the stuff that they can't do without.
I mean, the first instance, energy use, but in the wake of energy prices going up, you typically get food price increases. Those prices going up means that people, especially at the bottom of the income distribution are getting squeezed because they spent significant shares of their income on these essentials.
And at the same time, the windfall profits that are accruing in response to the price explosions very disproportionately benefit the richest of the rich. So as such, an energy price shock is actually a redistribution shock from the bottom to the top.
And then the question is, how do we respond to this policy-wise? And the standard response is hiking interest rates. Now, the declared goal of hiking interest rate is to cool down the labour market, which, you know, sounds like a fresh breeze on a hot summer day, but in reality it's meant to put people's jobs under pressure or even throw them out of work. If we say we need unemployment of four, five, six percent, this means literally throwing people out of their work, whose livelihoods are destroyed if they can no longer make a living by having a job, whose family's livelihoods destroyed, whose communities are destroyed.
And that is what I mean when I say, you know, casual acceptance of suffering because that's what's happening in, for example, the case of hiking interest rates and with the goal of cooling down the labour market.
John Letzing: Tell me a little bit about what is in the book in terms of how an anti-fascist economics might approach this differently than the way it's done now.
Isabella Weber: You already said like addressing economic insecurity, right, as like one of the key elements that can prepare the ground for far right promises appearing attractive.
So broadly speaking, it's about putting a floor under people's livelihoods and a ceiling on extreme forms of concentration of private and corporate wealth. And both of these elements are actually not something that I came up with, but that in the '40s, when economists were trying to understand what an economics of never again would have to look like, were part of a standard repertoire of many economists.
And in terms of putting a floor under people's livelihood, I am arguing that the starting point has to be the essentials. So it has to energy, housing, food, transportation and all sorts of forms of care, communication. So the things that people really need to make a living and be part of society.
And in fact, that the essentials have to be organised around the goal of a dignified life for all was key to the post-war consensus. So we see this in the German constitution, which of course wasn't explicitly anti-fascist constitution. Also called the foundational law because of the specific historical circumstances. But the first article is explicitly saying like human dignity may not be touched. And it's the responsibility of all state power to serve human dignity. And that, of course, includes the economy.
And I think it's quite clear that a dignified life requires having this floor under your livelihoods having, you know, access to affordable essentials.
One of the key theorists here is also Harold Lusky, who was the chief economist of the Labour Party in 1945 under Atlee's government, where he argued that whoever controls the essentials has a considerable amount of degree over the fate of society and economy, because not only people but also businesses depend on essentials like energy, like transportation, like communication, right? And therefore those essentials had to be publicly controlled because otherwise there always was this basic tension between, you know, private exclusive control over the essentials and democracy as ruled by the people for the people.
John Letzing: As you make clear in your book, not all prices are equal in terms of potential social impact, but when policymakers are addressing inflation as they do now, that means generally jacking everything up without sort of prioritising the particular prices and costs that you're talking about. So why is it done that way now? Why is more attention not paid to these fundamental costs that you're describing?
Isabella Weber: Kind of the sequence that we have been seeing in terms of inflation is that, you know, you get these spikes at the beginning of the value chain, most importantly, energy, then you get price spikes in food, then, you hike interest rates, and then one of the impacts of higher interest rates is higher mortgage rates and higher rents. So then you get a squeeze on the housing side.
So if you put those three things together, you really have core elements of a basket of essentials that are going up in price. And that means that people experience an economic insecurity shock in the sense that even people in the middle of the income distribution fear that their living standard is under threat. And it's not just a feeling, it's actually a reality if you look at how the prices of the stuff they can't do without are evolving in relationship to their incomes.
Now, the policy playbook that we have in response to inflation is one that is very much informed by the idea of inflation being demand driven, but the inflation that we have been living through has been an inflation that has been supply shock driven.
And if you have a supply shock and prices at the beginning of the value chain, most importantly, energy, but also, for example, computer chips, shipping, you know, shooting up, then the question is, how is the rest of the corporate sector responding to this? And what we have seen is that these cost shocks themselves have operated as a form of coordinating mechanism, or even in very concentrated sectors, before the shocks of the pandemic and the Russian attack on Ukraine, we have had a situation where despite massive amounts of quantitative easing, prices have actually been surprisingly stable. Corporate concentration was also already very, very high, yet prices were very stable because we had a form of basically oligopolistic competition, where large companies were competing primarily over market share by building out global supply chains that were becoming ever more efficient, ever more just in time. And with that, you know, if the demand for something went up, let's say the demand for cars goes up, then the car company doesn't go, oh, I'm going to increase my prices. No, I am going to use my global supply chain to deliver cars as quickly as I can to grasp as much of this market as I can.
Now, with these shocks, this has basically opened a window of opportunity for companies to start hiking prices in ways that at least protected their profit margins. Now, what happens if you protect your profit margins in response to a cost shock is actually that the unit profits go up. There's a nice study from the European Central Bank that illustrates this. This is basically a matter of accounting.
So if you put together price spikes at the beginning of the value chain because of the direct impact of these shocks and margin protection as the dominant form of response across the corporate sector with some firms actually also managing to increase their margins and some, I mean, a smaller share of the overall companies for the U.S. case anyway, taking a margin squeeze. But if you take all of this together, you get basically a situation where the profit share in the economy goes up. And that's what we have seen in the case of the U.S. where the unit profits per national income have been going up from around hovering between 12 to 14 cents before the inflation to around 18 cents after the shock and then jumped up again under Trump.
But the point being that this is what I've been calling seller's inflation in the sense that it's supply shocks that are propagated through the economy by the pricing decisions of corporations. And it's not an inflation that is simply driven by too much demand. I mean, you of course have to have a certain level of demand to sustain these price increases. But if it was just a demand increase, then we would be in the world that we were in when we were seeing quantitative easing and very stable prices.
John Letzing: What we're talking about essentially is the way that businesses operate and sort of short term versus long term thinking. And of course, this is a World Economic Forum podcast and the Forum has as one of its sort of core ideas, this concept of stakeholder capitalism, which just to boil it way down is essentially that businesses should take a much broader view of their impact on world than just making money for shareholders.
So I'm wondering, do you see any similarities between that and sort of what you're describing in the book?
Isabella Weber: Yeah, I mean, I think the contradiction that we have run into is that what's been the worst of times for the majority of people on this planet ended up being the most profitable of times for the large corporations that are running our essential sectors from, you know, fossil fuels to food commodity trading to shipping.
These are sectors that produce stuff that no one can do without and that yet in the context of the worst emergencies, the worst supply crisis that we have seen in a century, we're reaping record profits.
And I think this creates a real incentive problem because companies should improve their resilience, but in order to improve their resiliency, it can't be the case that a breakdown of resilience is the most profitable moment.
So that's why I actually think measures like When for-profit taxes and even where it is feasible, price stabilisation measures in the context of such emergencies can contribute to aligning the incentives of the companies that run those sectors with the needs of society as a whole to have a reliable provisioning of essentials.
John Letzing: So if somebody is listening to this or reading the book and if we're talking about sort of refocusing economies to pay more attention to providing those essentials for people, they might say, well, look, historically, there have been a lot of efforts at this, some more extreme than others. The Soviet Union, for example, had big effort towards full employment. Tell me a little bit about what those systems maybe got wrong and what is different between that and what you're describing in the book.
Isabella Weber: It of course depends which period in the Soviet Union we are talking about, but broadly speaking, the goal of Soviet economics was central planning of the whole economy, right? And that is very different from what I'm talking about.
What I'm taking about is greater public control over the sectors that economy and livelihoods depend on, so that we have those sectors be more shock resilient, have stabilisation and preparedness measures in place for those sectors, and so that we can transform them in ways that make the ways in which we produce stuff compatible with sustained life on this planet, namely to make it compatible with decarbonization and climate goals.
And it turns out that the essential sectors are extremely important here because they are also the most resource intensive, most energy intensive sectors that we have in our economy. So, you know, by transforming them, we actually move towards achieving the climate goals that we had failed to achieve and thereby have been, I mean, literally putting humanity at risk.
John Letzing: One of the things that you just mentioned is price control measures selectively applied maybe and of course for you, this is very interesting because you've broached this subject previously and some more conservative or traditional economists maybe got a little bent out of shape as a result.
Maybe can you tell me a little bit about that dynamic, this maybe reluctance among and more established economists and thinkers to something like that, which maybe what you seem to be saying is, look, selectively applied or however we want to do it in a smart way, we shouldn't necessarily throw out an idea from the past if we think it might work in the present.
Isabella Weber: So I think part of why economists react so, trying to find the right adverb here, I mean, part of why economists have such strong reactions to price controls is that the mental model that most economists use is the supply demand diagram. So of course we have much more sophisticated models with, you know, more variables and so on, but if you, you know, wake up an economist at night and ask them like, you know, what's, how does the economy work? Probably they will give you some version of the supply demand diagram, right?
So if you look at the world from that perspective, and you now do a price control, that this basically means that you have abolished the market, because in this diagram, the only thing that really represents the market is the price, there are no firms in there, there's no banking in there. There are no financial markets in there, there's no product development strategy, there's innovation, there's, you know, there's there's branding, there's conquering market shares and so on. It's just like literally the price mechanism.
Now, the good news is that in reality, markets actually have all of these things that I just talked about, right? So markets are much more than the price mechanisms. And, in fact, in a world of very high levels of corporate concentration as the one that we live in, it's not really a question of whether prices are controlled in many markets, not in all of them. I mean, for example, in oil, we have spot and future markets that are extremely volatile and where no single company controls the price. But if we talk about the price of smartphones or all of the devices that we are connecting over here, right, then I mean, these are products where prices are set very consciously.
So the point being that there's large parts of the economy where prices are actually set very actively. So then it's not really the question of, you know, pure market pricing in this abstract sense of what the supply demand diagram suggests. But it's rather the question of who is actually managing those prices.
And maybe their prices where the public should have a say, because on the demand side, people don't have much of a choice but to buy that stuff. So we don't demand elasticity. And in that sense, those prices are of a quite different type than the ways in which we think about prices more generally speaking.
I think another important thing to acknowledge is that in the last years, price controls have increasingly become a reality. A study just came out from the IMF that showed that one of the dominant forms of response to the energy crisis of recent years has been price control.
So we can either pretend like they don't exist and they are just the stuff of the devil or we can acknowledge that there can be situations where countries basically have to revert to them because they are necessary as an emergency tool and start asking the question of how can we design them in sensible ways? How can we have them as an effective tool in the toolbox?
There are no silver bullets. Price controls are no silver bullets. All they can do is buy time for measures that change the underlying structures that bring about the price explosions.
But buying time in an emergency, and we are living in an age of emergencies, is a pretty important thing to do. I mean, you know, like putting a bandage over a wound is not going to heal the wound, but it's a pretty thing to for the healing to take place. So in a similar way, price controls can be a useful tool in the toolbox.
John Letzing: And speaking of emergencies, I was hoping to get your take on the recent protests in France, which have been based on the educational system and cost of living concerns. I'm wondering, do you see that as a sort of predictable reaction to austerity or is it evidence of maybe the limitations of a more anti-fascist type of economics?
Isabella Weber: I mean, I think it's absolutely remarkable that we see like hundreds and thousands of people out in the street protesting over the cost of living, right?
So what people are saying is we can't take the status quo any longer. Like we go to work every day, we do our jobs and the stuff that we can do without the essentials are becoming so expensive that we are getting squeezed to the point that we, you know, see that the social contract that we have been relying on no longer works. And I think that's the underlying message of these protests.
And if you look at what's been happening, then for a long time, elites have been telling people that democracy is the greatest political system that has ever existed, which is of course true. But then in the second sentence have said, unfortunately, even when it comes to your most basic needs, there's not much that we as your elected representatives can do for you.
And even if we are in the middle of massive global shocks in a situation where you are struggling to pay your basic bills and at the same time, profits are climbing to record levels, unfortunately there's nothing that we can do. And if this happens, I think it should not be a surprise that people lose trust in democracy.
And if this frustration is not channelled into some form of a new deal that says, you know, the status quo is not tenable, but the extreme right is not the way to go. We need a new idea that puts a floor under people's livelihoods. If this is not happening, then you get the kind of outbursts that we are witnessing.
And of course this is connected to austerity and that is connected back to the ways in which we fight inflation. Because what we have seen is that with the monetary tightening, central banks have actually also been selling off bonds, and those bonds are now in the hands of financial institutions with a very volatile attitude towards those bonds. So that is, I mean, that's not the only source of the volatility in the bond markets, but it's one of the sources of the volatility in the market. And there is a link between our inflation policy regime and what's happening on bond markets.
So, in the European context, of course, there's also the challenge of fiscal European integration and, and all of that, which I mean we're kind of hitting hard at now. And we're like, I personally think that greater fiscal integration and more fiscal space is really the only way out for European democracy to sustain
That's kind of the cocktail that we are looking at, right? Like people being extremely frustrated, for, I think, good reasons. This is not vibes, this is something that we can see in the data very clearly. And where the status quo of the economic policy institutions in Europe really requires reform in the monetary and the fiscal space to make the kind of measures that are necessary to address a crisis possible.
John Letzing: Another nice turn of phrase in the book is needs are not vibes, right? Which is a very nice way of putting it, I think.
But in terms of, you know, actual solutions or maybe different ways that we could approach these problems, like affordability specifically, what are some things we can do there? I think one thing you get into in the books a bit is about the way that we have, most economies have established controlling the money supply is to sort of shelter or insulate, at least in theory, the people making those decisions from politics. But you're saying in the book, look, maybe that's not such a great idea. Maybe they should be more responsive to people, to politics. So is there room for improvement there or different ways of doing things?
Isabella Weber: Yeah, I mean, one of the themes in the book is the inflation of the 70s and 80s in the ways in which it's been settled, right? And it's being basically settled with the Volcker shock. But there was a different part there, which the Humphrey-Hawkins Act in the United States actually entailed, which was the dual mandate of the Fed, right. So
John Letzing: And we should say the Volcker shock, sorry to interrupt, but the Volker shock was essentially a dramatic jacking up of interest rates in a bid to fight inflation.
Isabella Weber: Yes, in ways that induced massive unemployment, that broke the power of the working class, that in the medium and long-term contributed to the erosion of unions, that unleashed the debt crisis in the global South that led to a decade of loss, development, and so on.
Now, in the United States, it was actually part of the civil rights movement that was an argument about the need for full employment and even a right to a job to be part of economic agenda to realise actual civil rights. Because what black communities had found is that whenever unemployment goes up, if average unemployment goes up it means that black unemployment is going up much more than white unemployment. So basically. Black communities were living in a perpetual unemployment crisis that got even deeper when overall unemployment went up, but that was never really resolved. So one of the key activists for the dual mandate was actually Coretta Scott King, the widow of Martin Luther King, and the march on Washington had been also a march for jobs, right?
So in the 70s, the Federal Reserve ended up including a somewhat watered down version of what this long-standing demand had been, but yet a mandate for full employment in central bank policymaking. And this mandate, of course, has been deprioritized. The most recent Fed has actually just started to deprioritize Black unemployment rates compared to some progress that had been achieved there in years before.
But I mean, to go back to your larger question, what I'm basically arguing is that monetary policy is too important to be insulated from democratic control and that we cannot say that this is just a matter of the technocrats where there is a universally correct rule and in fact, if we have an inflation fighting regime that only knows one tool, namely hiking interest rates, and one institution that only has one mandate, namely price stability, then by default that institution will be hiking interest rates when there's inflation, no matter what the nature of the inflation is.
And that is a real problem at this moment where shocks have become endogenous. It's no longer the case that they have one-off events. We are in a structural crisis of disintegration of, you know, the natural foundations, ecological foundations of our economy, the political institutions that have been holding together our global system, and even just, you know the basic global division of labour. And in this context, there will be more shocks. That has to be our working assumption.
John Letzing: In terms of ways of better dealing with this kind of thing that you describe in the book, another sort of callback to something from the past is this thing called countervailing powers. And I'm hoping maybe you can tell me a little bit about what that means and how that could be applied potentially today.
Isabella Weber: I mean, this concept of countervailing powers comes from John Kenneth Galbraith, one of the most important institutionalist economists of the 20th century. He had this theory that countervailing powers to the market would come about more or less spontaneously. If you have a growth of corporate power then you have growth of union power that goes along with it and therefore you know you have this like embedding of the economy in these countervailing powers.
What I'm arguing is that with what we have seen in terms of the erosion of countervailing powers, not least in terms what we just talked about with the Volcker shock, we have to revive this concept but see that it has to, that those countervailing powers have to be built up actively. And this is actually where the idea of countervailing powers connects with the idea of a counter movement in Karl Polanyi. Karl Polanii was one of the most important theorists of the rise of fascism in the 1940s. He wrote The Great Transformation, which many think of as a book about the Industrial Revolution, but was actually a book of the question of how can it be the case that free market capitalism? Tends to bring about tendencies of authoritarianism and even fascism.
And what he argued is that market fundamentalism carries what he calls a fascist virus in the sense that when governments intervene in the market with the best intentions, then the market fundamentalist paradigm will say that this is always bound to fail. It's always only going to bring about worse outcomes, even though it was started with the best intention.
So one example would be rent control, you know, where you can read in economics textbooks that the second worst thing that can happen to a city after dropping a nuclear bomb is rent control. So the idea is that governments do this with the vast of intentions, but actually they only create shortages in the housing market. Or another example is Milton Friedman's logic of saying that, you know, if you increase government spending, your goal might be to increase employment, but actually all that you are doing is to induce inflation.
So these are, you know, like there's always this like, you know, good intention that leads to something worse because you didn't understand that intervening in the market only makes things worse.
Now, what I mean, maybe to add one more, a bit more drastic example is Malthusian economics of the 19th century, where, you you have this idea of supply of food on the one hand, and supply of people on the other hand. And if the price of food goes up, then this means that this is out of whack. And if you intervene with famine relief or forms of price controls, then you are basically keeping people alive who should be dying because they are excess population. And then you're just like you know, creating a situation where they will multiply and then just more people will have to die, right? That's the most drastic and not just an abstract example, but an example that actually became a guiding principle in the El Nino famines of the 19th century and the background to what Mike Davis calls the Late Victorian Holocausts.
In any case, the point being that when you get to these moments of existential crisis, famine being the most extreme form, but unemployment crisis being another, you know, existential crisis and the kind of shocks and affordability crisis that we have been living through is also a version of an existential crisis.
That when this happens, there are counter movements that, you, know, emerge spontaneously. But then the question is how, what is happening with these counter movements and one possibility is that through state violence you keep imposing the market order even when this market order is delivering mass unemployment or a cost of living crisis that leads people to say we can't take it anymore.
And this form of state violence enabled imposition of the market order is what Polanyi identifies as the fascist route and that can, you know, lead into fascist forms of state control.
And the democratic route out is to, you give up on the market fundamentalist idea that there's nothing that can be done and start asking what is it that we can do to address the crisis? How can the state as the representative of the people act to secure the livelihoods of everyone. And that's what requires the building up of countervailing powers.
And that's basically what I am arguing for in the book by saying that an anti-fascist economics has to realise that people are saying we can't take the status quo anymore and we need to provide a democratic way out.
John Letzing: In terms of food specifically, an interesting aspect of your book that you bring up is this concept of food stocks and you get into a little bit of history here and I have to admit to you, I was not aware of the existence or almost existence of the World Food Board, that whole chapter of history. I'm hoping maybe you can tell me a little about the World Food Board and sort of what that says about potential solutions today in terms of food security.
Isabella Weber: After World War Two, the question was of course, how should the world order look like, right? Like what should the new economic order be?
And when it comes to the international economic order at Bretton Woods, there was an insistence that from Keynes, but even from people like Hayek, so there's actually there's a rare agreement between Keynes and Hayek that, you know, commodity prices are so volatile that this kind of volatility can unleash system-wide macroeconomic volatility.
And that's why Keynes specifically argued for forms of multilateral buffer stocks where you would be stabilising the prices of commodities with open market operations similar to a central bank.
So you would be buying when the supply is high and prices are falling, and you would be selling when prices rising and demand is high in relationship to supply. So you would basically be stabilising the demand supply relationship through this public stock holding system and thereby stabilising commodity prices and thereby actually helping especially commodity dependent economies to achieve greater macro stability, which would then have positive impacts on worldwide stability because of the interaction between commodity-dependent and non-commodity dependent economies.
Now, this was the broad vision for commodities in general. For food, specifically, the Food and Agriculture Organisation actually set out under John Boyd Orr, its first director, with this vision of a World Food Board, which would have done what I just described for food, adorable food staples, specifically grain.
John Letzing: Like a central bank for food, essentially.
Isabella Weber: Yeah. And I mean, when we say food, I mean food is such a broad heterogeneous category, right? Like, I wouldn't be a central bank for yoghourt, but there would be a bank for, you know, grains, dried beans, you kind of like durable, storable food commodities that are traded in commodity markets because they are durable and storable. And that as such have very volatile prices and where this volatility becomes a real challenge for farmers on the one hand and consumers on the other.
Now, I think that these proposals are incredibly relevant today because of climate change. We will be looking at massive food price volatility. We are already looking at massive food price volatility. And we have seen that even without actual global supply shortages, prices can spike in ways that creates a global malnutrition crisis. That's what's happened in 2022, 2023, right? When globally speaking, there was no shortage of supply. But the supply disruptions in terms of transportation routes and all the disturbances in the market alone were enough to send prices spiralling in ways that more than a decade in progress in the fight against malnutrition globally was reversed as a result of these price increases.
So that's why I've been arguing that we need to revive the stabilisation mechanism and the question then of course becomes at what level of administration does this make sense.
We have done a report for the G20 task force on food security. When the G20 was under the presidency of the South African government. So we use the example of the African Union and the African continent. And what we argue is that the level of stabilisation regime always has to match the market structure.
So in the African context, food commodities that are predominantly produced and traded regionally, like for example, cassava and some of these, like native forms of food staples that don't have global markets and in the same way as wheat or rice or corn does. For those we can have a regional buffer stock and can actually stabilise the prices regionally because these markets are not integrated. For rice and wheat and corn, you could canalise the imports into the African continent and have a joint procurement entity basically, where you import jointly and you import more when the prices are low and you store and then you are less dependent on imports when the price goes up. So you create a degree of resilience.
Now, if you create such public stockholding systems, you could use them as a lever for transformation in the agricultural sector, because you could incentivize the production of climate-friendly crops, climate-resilient crops, production that requires less water. You could combine it with fertiliser stockholding systems to transition out of fossil fuel-based fertilisers. And so you basically would have a lever that can be used for greening agriculture.
John Letzing: Now, the World Food Board, of course, ultimately that idea was scrapped. What are the odds, do you think, of something like that working or gaining broader appeal in the contemporary context?
Isabella Weber: I think that buffer stocks are already gaining greater appeal.
I mean, if we look at the ways in which the energy shock in the wake of the US attack on Iran, US Israeli attack on Iran has been handed, then we see that the release of served through the coordination of the International Energy Agency has been an important way of buffering that shock, and even more important that China actually has been kind of acting like a buffer stock to the world by massively reducing its own oil imports. And China actually has some of the largest buffer stock systems that probably have ever existed in human history as we speak.
In the European context, we see that the, you know, new European supply security strategy also has elements of buffer stocks. The Draghi report has ideas around buffer stocks for energy.
So the question really is, are these buffer systems going to be designed to only serve national security interests of the global North, or are they going to designed in ways that have a genuine stabilisation mandate in that also allows for development of the global south and that has this holistic kind of a vision.
John Letzing: Maybe a last question for you relates to what you talk about in the book related to international cooperation. And you describe this as an essential element of anti-fascist economics, of putting economies on a better course. There is, of course, a lot of pushback to that very notion. I think for a lot people, what maybe you and I would see as international cooperation, and they would see as some form of insidious world government.
So I'm wondering what your take is on why there is so much resistance to that idea and what we can do to work through that.
Isabella Weber: Thank you for bringing up this notion of world government. So, you know, in general, the spirit of my book is gradualist. So the general principle is to say the direction of travel is to put a floor under people's livelihoods in the ceiling on extreme forms of concentration and corporate power concentration in the economy.
But the way in which we get there is by, you know, starting with concrete things that can be achieved in the here and now. Thereby establishing the concept that change is possible, which I think for many people has become something that seems out of reach.
So I'm not envisioning that we are going to overhaul the world trade system in a heartbeat. But I do think, you know, we have been trapped in a dichotomy between free trade and nationalist protectionism, where free trade never has been really free behind, you know, the notion of free trade have always been very complex trade agreements with hundreds of pages that have been drafted by huge legal teams and have been heavily influenced by those who have the capacity to engage in these legal battles which have been predominantly multinational corporations and they often have done this in ways that even have constrained domestic democratic space for governments to act if we look at investor dispute settlements and these kinds of things.
Now what I am arguing is that the upshot of the fact that trade has always been managed through trade agreements is that we can also have trade agreements that are less biassed towards one set of interests and that actually know, take the interests of sustained life on planet Earth, namely the climate question into account systematically that take the interests of working people as the central question of how we organise trade to the benefit of all working people involved.
And in terms of what we have talked about, about buffer stocks, this is actually also a form of managed trade. It's not about, you know abolishing the market. It's not about abolishing international trade, but it's about steering trade in markets towards goals of greater stability in the here now and transformation of the ways in which we provision in the medium run.
So in that sense, this is really about working out concrete forms of managed trade In the interest of the majority of people and not about an instantaneous creation of a world government or something.
Robin Pomeroy: Isabella Weber was talking to my colleague John Letzing.
Please follow Radio Davos wherever you get podcasts and if you enjoyed this episode, please leave us a rating or review on whichever app you're using to listen to this.
This episode of Radio Davo was presented by me, Robin Pomeroy, with studio production by Taz Kelleher. We'll be back next week, but for now, thanks to you for listening and goodbye.
Democratic governments that fail to address cost of living pressures can fuel the rise of anti-democratic forces, says Isabella Weber, Associate Professor of Economics at the University of Massachusetts Amherst.
The author of the new book Anti-Fascist Economics describes the economic policies she says can ward off extremism.