Top economists agree: These are 5 thorny issues for the year ahead
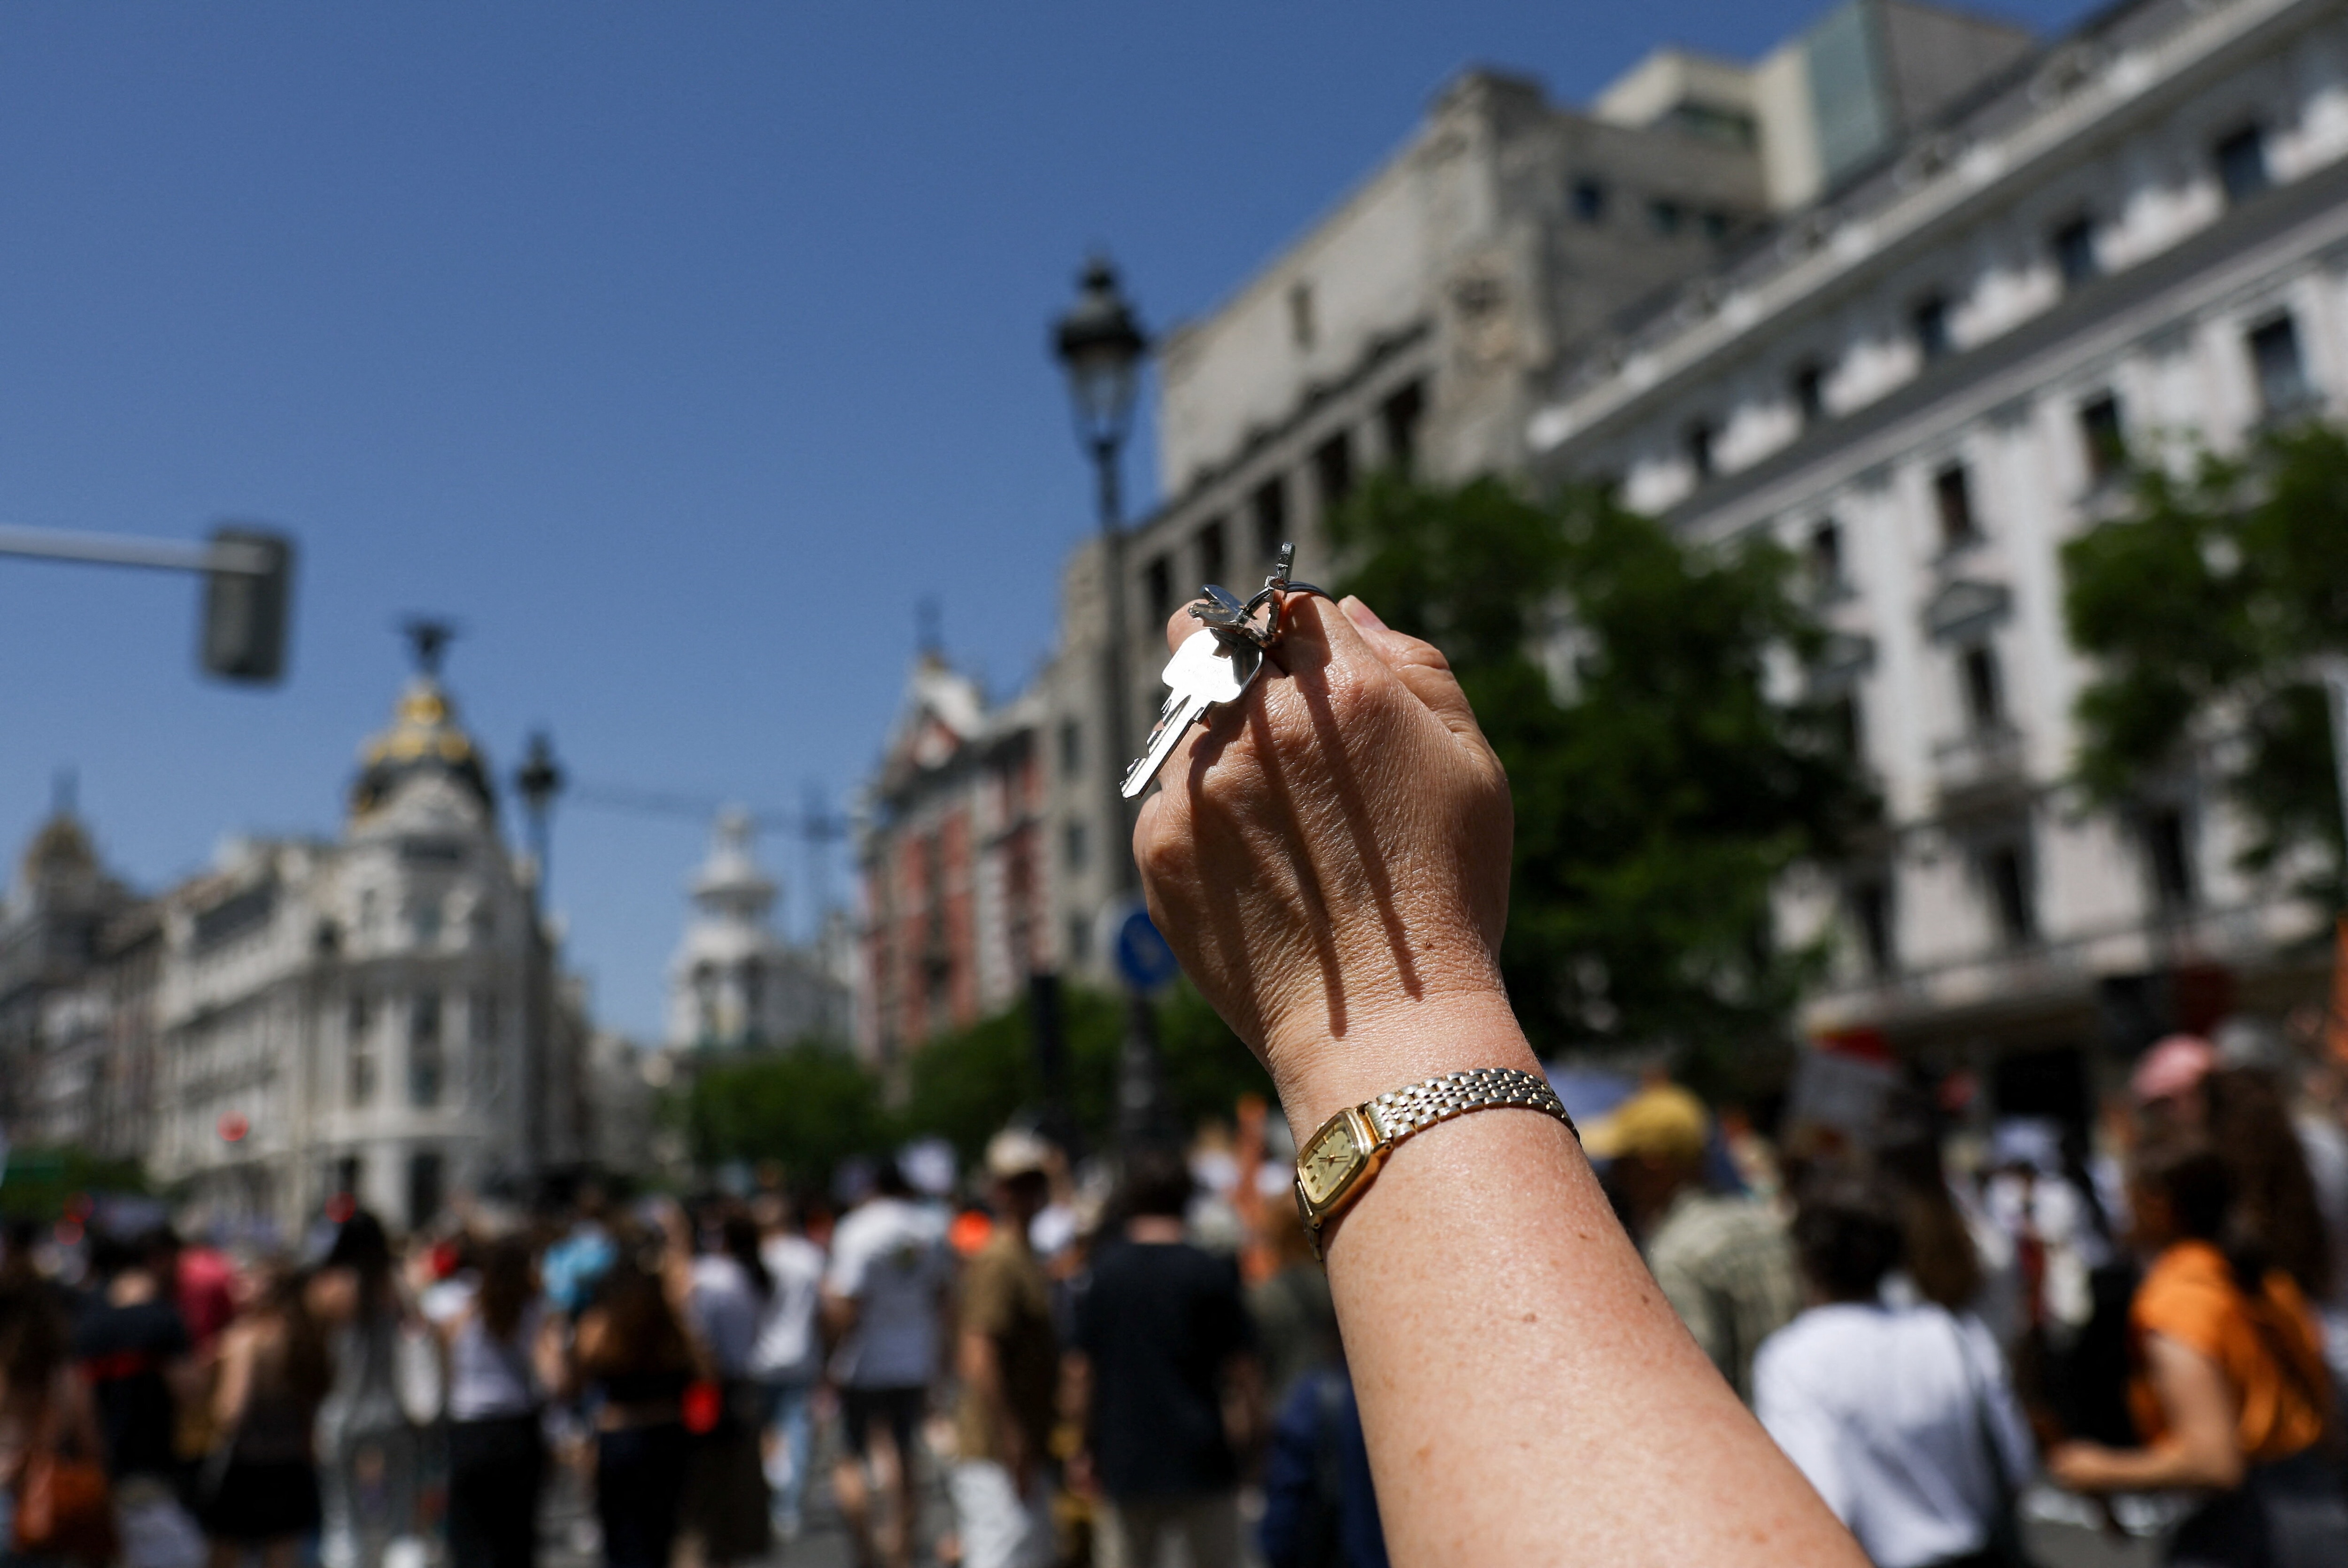
A cost-of-living protest in Madrid. Economists flag elevated prices as a problem likely to endure in many places. Image: REUTERS/Kacper Pempel
- A stretched global economy may ‘soon test the limits of resilience,’ according to the International Monetary Fund’s just-published World Economic Outlook.
- It follows the publication of the Forum’s most recent Chief Economists’ Outlook; a view through the prism of both defines a set of difficult issues likely to linger.
One of the world’s biggest economies is being told to “get your house in order,” government bonds have been dumped at levels unseen since Hotmail accounts dominated the internet, and stockpiles of oil relied on during the seemingly endless disruption of shipping through the Strait of Hormuz appear to be running dry.
Sure, the top-line numbers for the global economy, things like GDP growth or trade volume, appear resilient enough. But a bevy of slow-burning issues in the background are sucking up the oxygen at this week’s IMF-World Bank meetings – and were clearly top-of-mind for the economists who compiled the IMF’s just-published World Economic Outlook.
The new report places a clarifying overlay atop the latest edition of the Forum’s Chief Economists’ Outlook, which went live a few weeks ago. Based on this refined view, here are five things likely to dominate the headlines for (at least) the near future.
Borrowing: Essential, now more expensive
As long as we’ve had money, we’ve had borrowing.
Bonds are essential borrowed money, and bond investors might be the most important audience for a country’s economic performance. If they start booing by selling off a bond, costs for the country issuing it go up. Yes, at some point someone may have ponied up $10 for that bond, which pays $2 in interest every year, but the next investor may only be willing to part with $7 to help fund your government – while still expecting $2 annually in exchange for their willingness to take on more risk.
That difference between a bond’s shrinking value and the interest a country pays its buyer is called a “yield.” It’s an inverted measure of confidence. The latest Chief Economists’ Outlook was published in time to note that the yield for America’s benchmark government bond had poked above 5%, reaching its highest level since 2007. It remains elevated.
The US is not the only place having that kind of effect on investors. The yield on Japan’s equivalent bond hit its highest mark since 1996, France’s version pinged a level unmatched since 2002, and Germany’s approached 2009-era heights.
The IMF says in its report that bond yields are responding logically to a resurgence of inflation and “concerns about fiscal sustainability.” It also notes that this doesn’t just raise borrowing costs for wealthy countries; the knock-on effects also make things more difficult for the less-wealthy.
Too much borrowing already on the books
Governments have had to shell out on shifting priorities.
A certain amount of public debt is a necessity for funding basics like infrastructure and pensions. But as places like Poland and Germany respond to a more uncertain world with bigger outlays for defence, and places like Japan and China dedicate more funds to support ageing populations, the burdens are mounting.
In the UK, the costs of healthcare and welfare benefits have soared. After the financial crisis a couple of decades ago, debt there doubled to 70% of GDP. During the pandemic it reached 95%. That’s about where it remains today.
Big debt loads matter, because they can tie a government’s hands when it’s most needed to step into the breach.
The IMF says in its report that stabilizing public debt levels isn’t likely to happen, unless governments change up what’s “currently envisaged” policy-wise. Meanwhile any fiscal support necessary to prevent social instability should be “temporary” and “tightly targeted.”
That was a throughline in the Chief Economists’ Outlook: debt-choked governments might not be able to prop up economies in the same way when the next global shock hits. The private sector will have to muster more genuine productivity gains on its own.
The sting of a high cost of living
Here’s a glaring element of both reports: it’s not just governments eyeing their account balances more warily these days.
Even if overall inflation figures aren’t necessarily ratcheting up at an alarming rate anymore, so much has accumulated in recent years that many people, maybe most, are feeling the sting in some way.
Added pressures like Iran war-induced price spikes for food and the fuel necessary to deliver it have not helped.
Abrupt increases in the cost of necessities in many parts of the world have been felt most acutely by lower-income households, the IMF says in its World Economic Outlook. Cost-of-living crises tend to stir public unrest and push governments to do things “at odds with standard policy recommendations,” which is IMF-speak for “make things worse.”
The Chief Economists’ Outlook zeroed in on the effect that elevated costs have had on wages. “Real” wages, or the true amount that people take home after accounting for inflation, have ticked down significantly this year in the wealthiest countries, it noted.
Real hourly wages for American workers in non-management roles have stagnated; the average was $9.81 in August 2020, and by August of this year it was just 13 cents higher.
What’s super about AI, and what isn’t
It’s impossible to talk about the direction of the global economy without factoring in AI.
The chief economists surveyed by the WEF zeroed in on how much the technology will likely boost productivity soon (a lot), how much direct employment new infrastructure like data centres will create (not so much), and how much public pushback that infrastructure is likely to face (a great deal).
Even the technology’s biggest proponents have to acknowledge the risk involved in relying on it disproportionately to push markets and economies forward. It’s a lot of eggs in one basket. A statistic drawing attention lately: data centres seem to be the only private construction spending on the rise in the US. At the same time, opposing new data centre construction seems to be the only thing American politicians from both major parties can agree on.
Meanwhile many people seem to be waiting for the other AI shoe to drop, right on the heads of displaced workers. Universal basic income has been proposed as a solution; the experiences so far of early adopters have been a mixed bag.
The IMF notes in its report that the AI boom is having its own impact on bond yields; one factor making borrowing more costly for governments is the “increased competition” from companies blanketing markets with their own bonds, to fund heavy spending on things like chips and data centres. Why lend money to a cash-strapped government when this technology seems like a sure thing?
Tariffs as a feature not a bug
When US President Donald Trump made clear he was going to follow through on promises to hit just about every kind of trade partner with tariffs, it was greeted by many economists with consternation.
After all, this was a tool that peaked in the 19th century. How would a fresh barrage from the world’s biggest economy shake out in the 21st? The tariff blitz hasn’t been as dramatic as feared, and a highly globalized world has mostly adapted. Meanwhile the underlying goals motivating these taxes on imports, like boosting domestic production to cut dependence on foreign goods, can still seem elusive.
The IMF notes in its World Economic Outlook that eye-popping tariff rates unveiled by the US last year were scaled back, and companies have meanwhile redirected a lot of trade to “alternative destinations.” But it also says a “drag” from tariffs pushed projections for global trade-volume growth down to 4.6% this year, from 5% last year.
The chief economists surveyed by the WEF see increased tariffs in Europe in the coming year. That comes as the European Union’s trade deficit with China, or the difference between what it’s buying from that country and what it’s able to sell there, recently hit roughly 1 billion euros per day.
The chief economists also expected increased tariffs in the US, which is not surprising given the WEF's Outlook was compiled amid that country's renewed trade friction with Canada. Like Europe, the US administration has viewed tariffs as a means to reduce its trade deficit. But the most recent figures indicate that this is a work in progress.
Don't miss any update on this topic
Create a free account and access your personalized content collection with our latest publications and analyses.
License and Republishing
World Economic Forum articles may be republished in accordance with the Creative Commons Attribution-NonCommercial-NoDerivatives 4.0 International Public License, and in accordance with our Terms of Use.
The views expressed in this article are those of the author alone and not the World Economic Forum.
Related topics:

Forum Stories newsletter
Bringing you weekly curated insights and analysis on the global issues that matter.
More on Economic GrowthSee all

Rohail Iqbal
October 12, 2026


